Last Updated on September 7, 2026 by Nasir Hanif
A disregarded entity is a business the IRS does not treat as separate from its owner for federal income tax. The most common example is a one-owner LLC that hasn’t elected corporate taxation. The LLC still exists under state law, while its income and deductions generally flow onto the owner’s tax return.
| Key point | What U.S. business owners should know |
| Default federal treatment | A domestic LLC with one owner is generally treated as part of its owner’s tax return unless it elects corporate treatment. |
| Individual owner | Business activity may be reported on Schedule C, E, or F, depending on the activity. |
| Self-employment tax | An individual owner operating a trade or business generally pays self-employment tax on net earnings. |
| Employees and excise taxes | The LLC is treated separately for employment taxes and certain excise taxes. |
| Changing tax treatment | An eligible LLC can use Form 8832 to elect another federal tax classification. |
| State rules | State tax and LLC requirements can differ from federal treatment. |
How a Disregarded Entity Is Taxed in the United States
For a one-owner LLC owned by an individual, the business usually doesn’t file a separate federal income tax return. Instead, its income and expenses become part of the owner’s return. The correct schedule depends on the business activity. A typical operating business often uses Schedule C. Rental or certain investment activity may appear on Schedule E, while farming activity may use Schedule F.
If the LLC carries on a trade or business, the individual owner is generally subject to self-employment tax on net earnings. The tax classification doesn’t turn business profit into tax-free income.
Disregarded entity, one-owner LLC, can also be owned by another corporation or partnership. In that case, its activity is generally reflected as a division of its owner rather than on an individual Schedule C.
Federal Tax Status and Legal LLC Status Are Different
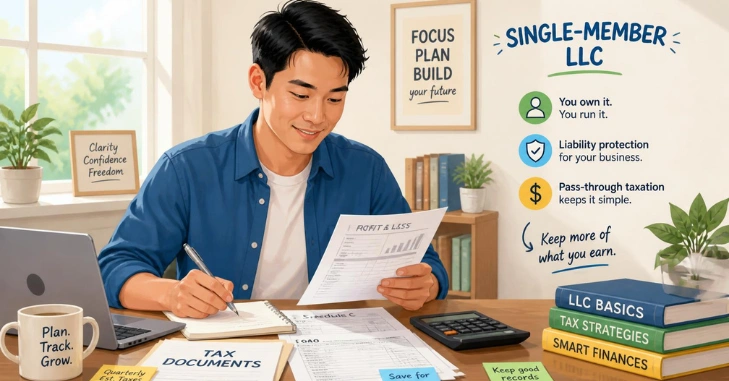
Federal tax treatment doesn’t erase the LLC created under state law. The company can remain legally separate from its owner even though the IRS combines them for federal income tax reporting. That distinction matters because LLC liability protection comes from state law, not from the federal tax classification. Owners still need to follow state formation, reporting, fee, and recordkeeping rules.
State tax treatment can also vary. A state may impose filing requirements, annual fees, franchise taxes, or other obligations even when no separate federal income tax return is required. The IRS advises LLC owners to check the rules in their state.
EIN, Payroll Taxes, and W-9 Rules
A one-owner LLC doesn’t always need its own employer identification number for federal income tax reporting. The answer changes when employees, excise taxes, or other filing requirements are involved.
For employment taxes and certain excise taxes, the IRS treats the LLC as a separate taxpayer. The company must use its own name and EIN for applicable payroll and excise filings, a point the IRS sets out in its guidance for single-member limited liability companies. Owners setting up payroll for the first time often review the rest of their back office at the same time, including managed IT services for business operations.
What happens on Form W-9?
IRS guidance says a U.S.-owned LLC using this default treatment generally reports the owner’s name on Line 1. The LLC name goes on Line 2. Line 3a reflects the federal tax classification of the owner.
This point often causes confusion because an LLC may have obtained an EIN for banking or another business purpose. That doesn’t automatically mean the EIN replaces the owner’s taxpayer identification number for every federal income tax form.
Can a Single-Member LLC Choose Corporate Taxation?
Yes. An eligible LLC can file Form 8832 to elect how it will be classified for federal tax purposes. One available choice is taxation as a corporation.
The IRS states that a classification election generally can’t take effect more than 75 days before filing. It also generally can’t be scheduled more than 12 months after filing. Certain late elections may qualify for relief. An eligible business seeking S corporation treatment can use Form 2553 to make an S corporation election.
Changing tax treatment can affect payroll, owner compensation, deductions, filing costs, and administrative work. A CPA, enrolled agent, or tax attorney can compare the choices using your actual profit and business plans.
A Simple Single-Member LLC Example
Suppose Maya owns a U.S. consulting LLC by herself. The company earns $90,000 in revenue and has $20,000 of deductible business expenses. If Maya has made no corporate election, the LLC normally follows the default federal classification. Assuming the consulting activity belongs on Schedule C, she would report the business activity with her individual federal return.
The $70,000 difference in this simplified example represents business profit before considering other tax adjustments. Maya may owe income tax and self-employment tax based on the applicable federal rules.
Now suppose she hires an employee. The payroll tax rules change the administrative picture. The LLC must use its own name and EIN for employment-tax reporting, even though its income-tax treatment remains unchanged.
Main Benefits and Tradeoffs
| Issue | Potential benefit | Point to watch |
| Federal filing | No separate LLC income tax return is usually required for an individually owned one-member LLC. | The owner must still report taxable business activity. |
| Tax structure | Income generally passes directly to the owner. | Trade or business earnings can face self-employment tax. |
| LLC structure | Federal income tax treatment doesn’t cancel the LLC created under state law. | State compliance must still be maintained |
| Administration | Default treatment requires no Form 8832 election. | Employees and certain excise taxes require separate LLC reporting. |
| Flexibility | Corporate taxation can be elected when appropriate. | A new election may add payroll and filing complexity. |
For many solo business owners, the appeal is the combination of an LLC structure with relatively direct federal income tax reporting. That doesn’t mean the default choice is always the most tax-efficient choice.
Foreign-Owned U.S. LLCs Need Extra Attention
A U.S. LLC wholly owned by a foreign person can face special information-reporting rules. IRS guidance states that a foreign-owned U.S. domestic entity covered by these rules may need Form 5472 attached to a pro forma Form 1120.
Those requirements differ from the normal filing process for a U.S. individual who owns a one-member LLC. Foreign owners should review current IRS instructions and obtain professional U.S. tax advice before filing.
A Practical Checklist for U.S. Owners
Before deciding how your LLC should file, confirm these points:
- Check that the LLC has only one owner.
- Confirm whether any corporate tax election has already been filed.
- Identify which federal schedule reports the business activity.
- Determine whether the LLC needs its own EIN.
- Review employment and excise-tax obligations.
- Complete W-9 forms using the correct owner information.
- Check your state’s LLC and tax requirements.
- Get specialist advice if the LLC has foreign ownership.
Keeping these questions separate prevents a common mistake: assuming one tax classification controls every legal and tax obligation.
More Business Resources on NewsPab
Business structure is one part of running a company. Owners working on growth can also review NewsPab’s guidance on local business SEO strategies and marketing outreach planning.
What Do We Do Next
Start by checking how your LLC is classified on your latest federal filings and confirm whether it is treated as a disregarded entity for federal income tax purposes. Then verify your EIN, payroll, W-9, and state requirements to ensure your business records are accurate and up to date.
If you’re considering an S corporation or C corporation election, compare the potential tax costs and administrative responsibilities before making a change from disregarded entity treatment. For foreign ownership, employees, major profits, or unusual transactions, review your situation with a qualified U.S. tax professional.
Frequently Asked Questions
A domestic one-owner LLC generally receives this federal income-tax treatment by default unless it elects to be taxed as a corporation. Special situations can create different rules.
Usually not when an individual owns it and no corporate election applies. The owner generally reports the activity on the appropriate schedule attached to the individual federal return.
Not in every case. An EIN is required for certain obligations, including employment-tax reporting and specified excise taxes. Banks, states, or other business needs can create additional reasons to obtain one.
An eligible business can make an S corporation election using Form 2553. Whether that choice saves money depends on profit, compensation, payroll costs, and other facts.
The federal income-tax classification and the LLC’s state-law existence are separate issues. State law governs formation and liability rules, so owners should maintain their company according to applicable state requirements.